High-net-worth borrowers may assume that substantial income and assets guarantee mortgage approval by banks at any loan size. However, when financing moves into super jumbo territory (at least $3M), the bank’s hands may be tied due to capital deployment and portfolio exposure constraints. Understanding why banks cap super jumbo loans can help borrowers set proper expectations about their chances of approval.
The $5M Surprise Rejection
A mortgage applicant earning $2 million annually with $10 million in liquid assets may receive enthusiastic pre-approval from their private bank for a $1.5 million mortgage. When that same borrower pursues a $5 million mortgage approval, however, the response often shifts from immediate approval to either conditional approval with reduced leverage or outright decline. This disconnect frustrates borrowers who assume their financial profile would justify unlimited borrowing capacity.
The issue is not credit quality or income verification. It is institutional capacity modeling. At higher loan balances, lenders must account for portfolio concentration limits, capital allocation per transaction, and loss severity calculations that increase materially with loan size. A borrower may be highly qualified, but if the loan represents disproportionate exposure relative to the institution’s capital reserves or concentration thresholds, approval becomes constrained regardless of the applicant’s strengths.
This dynamic explains why super jumbo loan denials occur even for borrowers with pristine financial profiles. The constraint is not personal qualification but institutional capacity and risk tolerance at scale.
Why Banks Cap Super Jumbo Loans
Institutional Exposure Limits
Banks operate under regulatory frameworks that require capital reserves proportional to their lending exposure. When a single mortgage reaches $5 million or $6 million, levels commonly associated with super jumbo financing, it can represent a material percentage of a community or regional bank’s total mortgage portfolio. Regulators monitor concentration risk by flagging loan categories that exceed defined capital thresholds, and banks establish internal thresholds well below these regulatory limits to maintain operational flexibility.
High balance mortgage limits are not arbitrary. They reflect calculated exposure modeling designed to prevent portfolio imbalance. A bank with $500 million in mortgage loan balances may comfortably approve fifty $1.5 million loans, but five $6 million loans create concentrated exposure that consumes disproportionate capital and introduces risk into the portfolio. Capital allocation per borrower becomes a binding constraint, even when the borrower presents minimal credit risk.
Institutions manage this through internal concentration controls that cap individual loan sizes, limit exposure to specific property types or regions, and require committee-level approval for transactions above defined thresholds. These principles align with bank capital allocation principles that prioritize portfolio stability and risk-weighted asset management.
Leverage Sensitivity at High Loan Sizes
Why jumbo loans get declined at higher balances often relates to loss severity modeling rather than likelihood of default. An 80% LTV loan on a $1.5 million property represents $1.2 million in exposure with a potential loss of $300,000 in a severe default scenario.
On the other hand, an 80% LTV loan on a $6 million property represents $4.8 million in exposure with a potential loss of $1.2 million under comparable stress conditions.
This is why 80% leverage at $5 million differs fundamentally from 80% leverage at $1.5 million. The percentage may be constant, but the capital required to support that exposure increases disproportionately as jumbo loan size limits approach or exceed institutional concentration thresholds.
Regional Risk Adjustments at High Balances
Geographic risk introduces an additional constraint layer at institutional-scale loan levels. Florida coastal properties face hurricane exposure, insurance carrier volatility, and condominium structural considerations that amplify capital sensitivity when loan sizes reach $4 million or higher. Private banks serving Florida markets often impose stricter LTV limits or require enhanced reserves for high-balance mortgages on barrier island or coastal zone properties.
California fire-zone properties encounter parallel challenges. Insurance sensitivity in high-risk fire areas creates collateral valuation uncertainty, and lenders respond by capping leverage or declining participation entirely when loan balances exceed portfolio concentration comfort levels. These regional adjustments are rational responses to geographic concentration risk compounded by large loan size to geographic concentration risk compounded by high loan balances.
Institutional capital allocation becomes increasingly conservative as loan size and regional risk factors converge. A $1.5 million mortgage in a fire zone may receive approval at 75% LTV, while a $5.8 million mortgage on a comparable property faces 65% LTV caps or outright decline from the same institution.
Take a Structured Underwriting Approach
If you are trying to get approved for a super jumbo loan, it is important to avoid chasing the lowest rate. At this level, approval is less about rate and more about structure.
A structured underwriting approach simply means planning ahead before you ever go under contract (for a purchase) or submit your loan application (for a refinance).
The steps entail:
- Review your full financial picture upfront
- Determine how much leverage is realistically available
- Decide which documentation method makes the most sense
- Identify which lenders are actually built to handle your loan size
Large banks and private banks don’t just look at you.
They also look at their own balance sheet.
For example:
- A bank may decline a $5M loan not because you don’t qualify…
- But because they already have too many loans in that price range.
- Or too much exposure in that geographic area.
- Or too many jumbo loans on their books this quarter.
Another institution with a different portfolio mix may approve the exact same file immediately.
That’s not about credit. That’s about internal limits. A structured approach identifies that before you apply. If you walk into a bank without thinking through these issues, you may get declined even though you’re fully capable of repaying the loan.
If your $4M–$6M loan was capped at a lower amount or declined, it may not be an income problem. It may be a structure and lender-fit problem.
Five Super Jumbo Constraints We Solved
$4.29M Bank Statement Loan After Two Bank Denials (Florida)
A CEO of a family-owned company with substantial liquidity approached two private banks for a $4.29 million mortgage to purchase a new home in West Palm Beach, Florida. Both institutions declined based on his high debt-to-income ratio. Their underwriting guidelines were inflexible and only accepted tax returns for income qualification.
We introduced him to a non-QM lender that flexibly allowed income to be shown through alternative documentation. His DTI, when using his business bank statements, was less than 15%.
Read more about this super jumbo alt-doc case study.
$6.15M Loan at 75% LTV After Bank Capped Him at $4M (Florida)
A CEO of a real estate investment firm sought a $6.15 million loan from his private bank to purchase a second home in Longboat Key, Florida. However, his bank’s internal concentration limits prevented approval above $4 million regardless of the borrower’s qualifications. This represented a classic capital allocation constraint rather than a credit concern.
We connected him with a private bank with portfolio capacity for super jumbo exposure in Florida coastal markets.
Read more about this second home super jumbo example.
$4.96M Loan Capped at $3M Elsewhere (California)
A surgeon with substantial income and assets applied to multiple institutions, but they capped him at a maximum loan amount of $3 million. He was seeking nearly $2 million more, a $4.96 million loan amount to purchase a new home in Laguna Beach, California. The constraint was neither income nor credit-based, but rather was due to institutional exposure limits that capped individual loan sizes below the requested amount.
We submitted his loan application to a private bank with more flexible concentration thresholds and portfolio composition guidelines.
Read more about this $4.96M super jumbo execution.
$5.8M Loan at 80% LTV in Fire Zone (California)
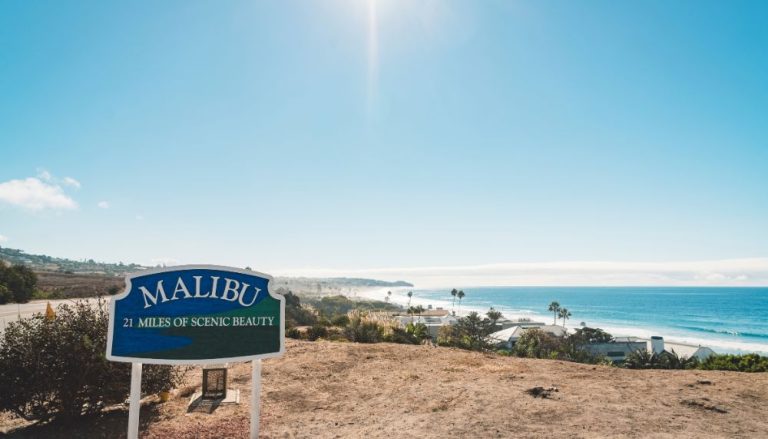
Our client, a highly compensated executive, was under contract to purchase a new home in Malibu, California for $7.25 million. However, he was declined by three private banks because the property was located in a fire zone.
We found a lender that had the risk appetite for super jumbo loan sizes for properties with exposure to wildfires.
Read more about this California fire-zone super jumbo case.
$3.74M Bank Statement Loan (Florida)
A successful entrepreneur was under contract to purchase a new home in Miami, Florida for $5.75 million. He required certainty of execution within a compressed closing timeline, but conventional sources could not provide definitive approval within the required timeframe.
We cleared his loan to close in less than 3 weeks, using his business bank statements to show his income.
Read more about this Miami super jumbo purchase example.
FAQs – Bank Limitations on Super Jumbo Loans
Why do banks cap super jumbo loans?
Banks cap super jumbo loans due to capital allocation constraints and portfolio concentration limits. A single $5 million mortgage can represent material exposure relative to total portfolio size. Institutions establish internal concentration thresholds to maintain operational flexibility and prevent over-concentration in high-balance transactions.
Can you get 80% financing on a $5M home?
Yes, but it requires identifying capital sources with an appetite for such high leverage. Many lenders cap LTV in the mid-60% range at higher loan sizes due to loss severity and capital constraints. Approval at 80% requires exceptional financial strength and substantial reserves.
Why would a bank cap or decline a super jumbo loan?
A bank may cap or decline super jumbo loans due to institutional capacity constraints rather than borrower credit concerns. Individual loan size limits and concentration thresholds can trigger automatic decline regardless of qualification. Capital allocation principles require portfolio diversification that large exposures can violate.
Are Florida coastal homes harder to finance at high balances?
Florida coastal properties face elevated scrutiny at higher loan sizes due to hurricane exposure and insurance volatility. Lenders may impose stricter LTV limits for high-balance mortgages in coastal zones. A property approved at 75% LTV at $2M may face 65% caps at $5M.
Are California fire-zone homes harder to finance?
California fire-zone properties encounter constraints at higher loan sizes due to insurance sensitivity and valuation uncertainty. Lenders reduce leverage when loan balances exceed portfolio thresholds. A $1.5M fire-zone mortgage may receive standard terms, while $5M requests face reduced leverage or decline.
What is structured underwriting?
Structured underwriting is a capital positioning discipline that matches transaction characteristics to institutional appetite and portfolio capacity. It begins with pre-underwriting before property selection, evaluating leverage capacity, and documentation pathways across multiple capital sources with different concentration thresholds.